Metal Fiber Market Size, Share and Growth 2026-2034
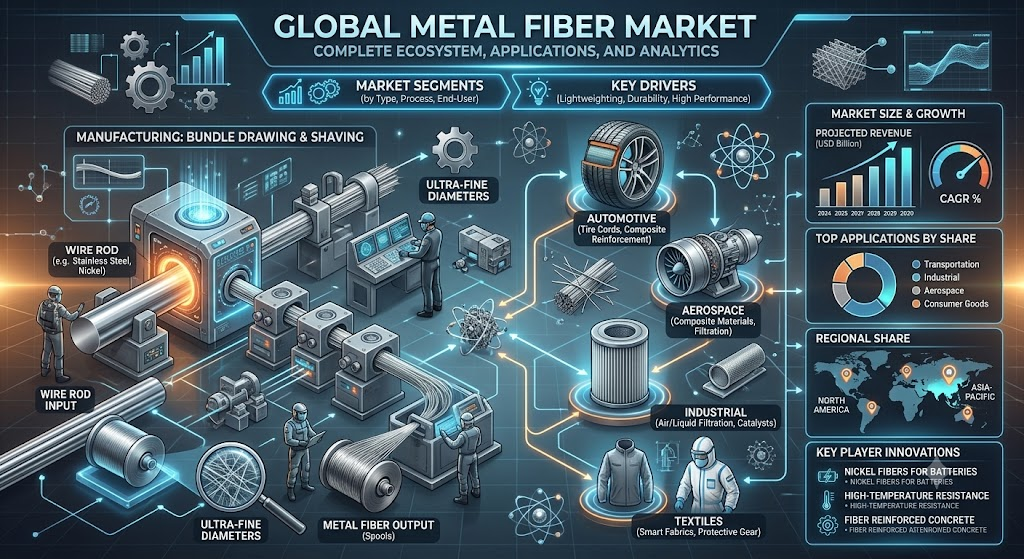
Market Overview:
According to IMARC Group's latest research publication, "Metal Fiber Market: Global Industry Trends, Share, Size, Growth, Opportunity and Forecast 2026-2034", The global metal fiber market size reached USD 5.4 Billion in 2025. Looking forward, IMARC Group expects the market to reach USD 7.3 Billion by 2034, exhibiting a growth rate (CAGR) of 3.19% during 2026-2034.
This detailed analysis primarily encompasses industry size, business trends, market share, key growth factors, and regional forecasts. The report offers a comprehensive overview and integrates research findings, market assessments, and data from different sources. It also includes pivotal market dynamics like drivers and challenges, while also highlighting growth opportunities, financial insights, technological improvements, emerging trends, and innovations. Besides this, the report provides regional market evaluation, along with a competitive landscape analysis.
How Technological Innovation and Industrial Demand Are Reshaping the Metal Fiber Market
- Steel holds the largest share in the metal fiber type segment, supported by its high availability, durability, and use across filtration, automotive, aerospace, and concrete reinforcement applications.
- Bundle drawing dominates the technology segment due to its scalability and efficiency in producing uniform, high-quality fibers across a wide range of metals.
- The automotive end use industry leads the market, with metal fibers used in exhaust systems, brake pads, battery electrodes, and advanced filtration units. Global automobile sales exceeded 26.3 million units, representing a 5% rise from 2020, directly driving product adoption.
- Asia Pacific holds the largest regional share, driven by rapid industrialization in China, Japan, India, and South Korea, and the region's role as a major hub for automotive production and electric vehicle development.
- In January 2026, Bekaert launched Dramix Loop, the world's first steel fiber made from end-of-life tire cords at industrial scale, reducing the carbon footprint of concrete reinforcement by up to 80% compared to traditional methods.
Download a sample PDF of this report: https://www.imarcgroup.com/metal-fiber-market/requestsample
Key Trends in the Metal Fiber Market
- Significant Technological Advancements in Manufacturing: Innovations in production techniques are making metal fiber manufacturing more efficient, cost-effective, and consistent. For instance, 3D printing integrated with metal fiber production can cut material waste by up to 90%, as thermoplastic materials used in advanced printers can be melted and reused, reducing resource consumption and preventing landfill buildup. These advancements are directly enabling higher quality output at lower operational costs.
- Rising Adoption in Smart Textiles and Protective Clothing: The expansion of the textile industry is creating significant new opportunities for metal fibers. Their electrical conductivity, flexibility, and structural strength make them ideal for use in smart textiles, wearable electronics, and high-performance protective garments used in defense, industrial safety, and sports applications. This trend is widening the addressable market for metal fiber producers beyond traditional heavy industries.
- Growing Demand for Lightweight and High-Strength Materials in EVs: The global electric vehicle industry is projected to grow at a substantial rate during the forecast period, significantly raising the need for metal fibers in battery applications, exhaust filtering systems, and electrode components. Metal fibers are being increasingly used in EV manufacturing because they offer superior heat resistance, electrical conductivity, and mechanical durability compared to conventional materials.
- Environmental and Regulatory Pressures Accelerating Filtration Applications: Stringent regulations such as Euro 6 emission standards for vehicle emissions in Europe have made advanced filtration solutions necessary. Metal fibers, known for their high chemical resistance, heat tolerance, and high porosity of up to 92% void space for low-pressure drops, are becoming the material of choice in automotive exhaust filtration and industrial emission control systems.
- Increasing Collaborations and R&D Activities by Key Players: Leading companies in the market are actively pursuing strategic alliances, mergers, and acquisitions to strengthen their market position and develop next-generation metal fiber products. These activities are focused on improving conductivity, tensile strength, and durability of fibers for deployment in critical sectors including aerospace, power electronics, and construction.
Growth Factors in the Metal Fiber Market
- Expansion of the Automotive and Aerospace Sectors: The automotive and aerospace industries impose rigorous demands for lightweight, high-strength, and thermally stable materials. In the automotive industry alone, global automobile sales exceeded 26.3 million units, with continued year-on-year growth, driving the sustained adoption of metal fibers in structural components, brake systems, and filtration. In aerospace, metal fibers are increasingly used in engine filtration and high-temperature structural composites, areas where no conventional fiber can match their performance.
- Infrastructure Development and Construction Activity: The rising demand for steel fibers from the construction sector is a key growth driver for the metal fiber market. Steel fiber reinforced concrete, which incorporates metal fibers to improve crack control, impact resistance, and fatigue life, is gaining adoption globally in tunnels, industrial flooring, bridges, and underground structures. In a documented project at SMP Automotive in Alabama, the use of Dramix steel fibers replaced traditional rebar, delivering significant cost savings.
- Regulatory Push Toward Low-Carbon and Sustainable Materials: Government and institutional sustainability mandates are compelling manufacturers across the automotive, construction, and aerospace sectors to shift to recyclable and lower-emission materials. Metal fibers, which are more recyclable than conventional synthetic fibers, are benefiting from this shift. Frameworks such as the EU Taxonomy, LEED, and BREEAM compliance requirements are actively driving demand for sustainable metal fiber solutions in construction and industrial projects.
- Growth of the Electronics and Power Sector: Metal fibers, particularly copper and nickel fibers, are critical in the power and electronics segment for electromagnetic interference shielding, thermal management, and electrical conductivity applications. In February 2025, Interstate Specialty Products launched a new series of metal fiber-based thermal management materials designed to improve heat dissipation and extend the lifespan of sensitive electronic components, responding to increasing demand from the miniaturized electronics industry.
- Asia Pacific Industrialization and Manufacturing Scale: Asia Pacific leads the global metal fiber market on the strength of its industrial scale, infrastructure investment pipeline, and dominant position in automotive and electronics manufacturing. Countries like China, Japan, India, and South Korea are making significant investments in technological development and industrial expansion. In December 2022, Tata Motors signed a contract for the delivery of 5,000 XPRES-T EVs, reflecting the region's accelerating EV adoption, which in turn drives demand for metal fibers in battery and filtration applications.
Leading Companies Operating in the Global Metal Fiber Industry:
- Addas Group
- ArcelorMittal S.A.
- BinNova GmbH and Co KG
- Fibrometals SRL
- Green Steel Group
- Guven Metal
- IntraMicron Inc.
- MBC Metal Limited
- N.V. Bekaert S.A.
- Nikko Techno Ltd.
- Nippon Seisen Co. Ltd
- Stanford Advanced Materials
Metal Fiber Market Report Segmentation:
Breakup By Type:
- Steel
- Copper
- Nickel
- Aluminium
- Others
Steel accounts for the majority of the market share due to its combination of affordability, availability, and durability across a wide range of industrial applications including filtration, automotive, aerospace, and construction.
Breakup By Technology:
- Bundle Drawing
- Foil Shaving
- Machining
- Melt Spinning
Bundle drawing holds the largest share of the industry due to its scalability and efficiency in producing large quantities of high-quality fibers with consistent thickness and strength from a variety of metals.
Breakup By End Use Industry:
- Automotive
- Textile
- Aerospace
- Construction
- Power and Electronics
- Others
Automotive represents the leading market segment, as metal fibers are widely used in exhaust systems, brake pads, and advanced filtration units that enhance vehicle safety, fuel efficiency, and performance.
Breakup By Region:
- North America (United States, Canada)
- Asia Pacific (China, Japan, India, South Korea, Australia, Indonesia, Others)
- Europe (Germany, France, United Kingdom, Italy, Spain, Russia, Others)
- Latin America (Brazil, Mexico, Others)
- Middle East and Africa
Asia Pacific leads the market, accounting for the largest metal fiber market share, driven by substantial infrastructure investments, strong industrial growth, and the rapid expansion of automotive and electronics manufacturing across China, Japan, India, and South Korea.
Recent News and Developments in the Metal Fiber Market
- January 2026: Bekaert launched Dramix Loop, described as the industry's first steel fiber produced from end-of-life tire cords at industrial scale. The product reduces the carbon footprint of concrete reinforcement by up to 80% compared to traditional rebar-based solutions and supports LEED, BREEAM, and EU Taxonomy compliance, positioning Bekaert as the first company to commercialize circular steel fiber production at this scale.
- November 2025: Bekaert and EMSTEEL signed a strategic partnership agreement at the Middle East Iron and Steel Conference in Dubai to advance the production and commercialization of high-end, sustainable steel products and solutions made with UAE-manufactured steel. The collaboration includes plans for Bekaert to produce its Dramix steel fiber reinforced concrete solutions using locally made EMSTEEL wire rod and to jointly promote sustainable construction materials across GCC markets.
- March 2025: Magnetic Shield Corporation launched a new metal fiber-based electromagnetic interference shielding technology designed to address the growing demand for efficient EMI shielding in miniaturized electronics. The technology was developed to improve performance in compact electronic devices, targeting a market segment where conventional shielding materials face significant limitations.
Note: If you require specific details, data, or insights that are not currently included in the scope of this report, we are happy to accommodate your request. As part of our customization service, we will gather and provide the additional information you need, tailored to your specific requirements. Please let us know your exact needs, and we will ensure the report is updated accordingly to meet your expectations.
About Us:
IMARC Group is a global management consulting firm that helps the world's most ambitious changemakers to create a lasting impact. The company provides a comprehensive suite of market entry and expansion services. IMARC offerings include thorough market assessment, feasibility studies, company incorporation assistance, factory setup support, regulatory approvals and licensing navigation, branding, marketing and sales strategies, competitive landscape and benchmarking analyses, pricing and cost research, and procurement research.
Contact Us:
IMARC Group
134 N 4th St. Brooklyn, NY 11249, USA
Email: sales@imarcgroup.com
Tel No: (D) +91 120 433 0800
United States: +1-201-971-6302